Dave Ramsey Reveals The 4 Things He Keeps In His Wallet
Dave Ramsey
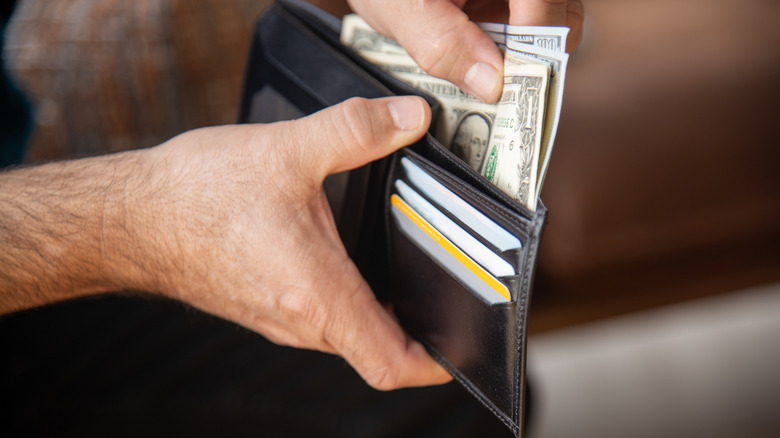
Longtime financial pundit, Dave Ramsey, has a unique approach to money management built on a string of personal setbacks experienced early in his career. After over relying on lending products to scale his real estate portfolio at a rapid pace, he had to declared bankruptcy (a process that can help people get a fresh financial start but is often misunderstood) in order to create an exit strategy from his debt. Since then, he has been outspoken about how this experience has impacted his subsequent financial decisions. This is perhaps best seen in the simplified wallet he carries. In addition to cash, Ramsey carries just four essentials in his wallet: two debit cards (one personal and one for his business account), his driver's license, and a firearm permit.
This minimalist setup makes it easier for Ramsey to decide how to pay for something, but it also lacks an item that's common in many other wallets — credit cards. According to Experian, Americans averaged 3.7 regularly used credit cards in 2025. However, Ramsey carries none because he believes it's too easy to be burned by over relying on borrowed money — something he learned firsthand. In fact, one of the central goals of Ramsey's financial 'Baby Steps' program is eliminating debt in order to build a stronger financial foundation.
Dave Ramsey's aversion to credit cards can be emulated by anyone
Dave Ramsey avoids credit cards because he believes even responsible use can lead to overspending (via Ramsey Solutions). It's far too easy to dig yourself into debt with borrowed money and then have to limit other parts of your life while paying it back. Similarly, once a balance has been established, lenders are eager to let you pay back a small monthly amount rather than the full debt. Paying only the tiny monthly payment obligation can balloon your total repayment figure by orders of magnitude over a short space of time.
While some of Dave Ramsey's financial advice has drawn criticism over the years, he often says that "the borrower is slave to the lender" (via Dave Ramsey). Fortunately, you don't have to already be debt free to take credit cards out of circulation in your wallet. Cutting up a card can create a physical barrier that may help reduce the temptation to use it. In general, setting credit cards aside, as Ramsey recommends, can encourage people to live more closely within their means. If you don't have the cash to pay for something, you don't buy it. This can help ensure that paying down existing credit card balances won't be offset by new spending. Plus, you'll steadily make progress towards firmer financial footing while building stronger budgeting habits all at once.
Prices, rates, and rules change. This is reporting, not personal financial, tax, or investment advice.